Insights
Can Company Partners Withdraw Money from the Company at Any Time? Partners’ Current Account and Tax Risks
Particularly in family-owned businesses and companies where shareholders actively participate in management, the distinction between corporate bank accounts and shareholders’ personal expenses can sometimes become blurred.
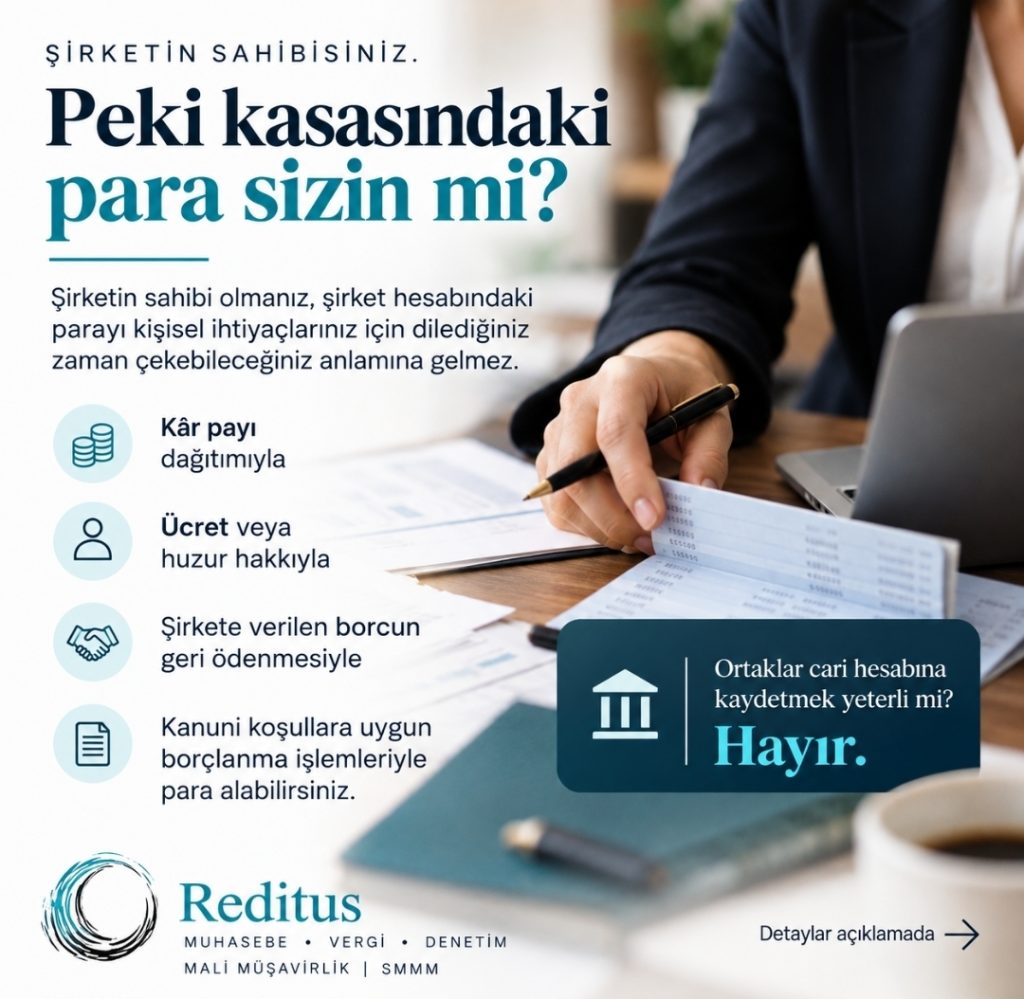
However, limited liability companies and joint-stock companies are separate legal entities from their shareholders. The money held in a company’s cash accounts or bank accounts does not directly belong to the personal assets of its shareholders.
Therefore, every transfer of funds from a company to a shareholder must have a valid legal, financial, and tax-related justification.
How Can Shareholders Legally Withdraw Money from a Company?
Shareholders are not entirely prohibited from receiving money from their companies. However, the nature of the transaction determines which rules apply.
1. Dividend Distribution
If the company has distributable profits and the necessary corporate resolutions have been adopted, dividends may be distributed to shareholders. Dividend distributions must be carried out in accordance with applicable tax obligations.
2. Salary and Board Remuneration Payments
Shareholders who actively perform duties within the company may receive salaries or board remuneration, depending on the nature of their responsibilities and services. The legal basis, documentation, and taxation of these payments are important considerations.
3. Repayment of Loans Previously Provided by Shareholders
If a shareholder has previously lent money to the company, the company may repay this genuine and properly recorded debt. This transaction should not be confused with a shareholder obtaining a new loan from the company.
4. Borrowing Money from the Company
Loans granted by a company to its shareholders are subject to the conditions established under the Turkish Commercial Code. In addition, such transactions may need to be evaluated under the arm’s length principle for tax purposes.
What Is a Shareholder Current Account?
In accounting practice, financial relationships involving receivables and payables between a company and its shareholders are recorded in the relevant accounts according to the nature of each transaction.
Under the Turkish Uniform Chart of Accounts:
- Account 131 – Receivables from Shareholders: Used to record and monitor amounts owed to the company by its shareholders.
- Account 331 – Payables to Shareholders: Used to record and monitor amounts owed by the company to its shareholders.
However, an important distinction must be made:
Recording a transaction in the accounting records does not, by itself, establish that the transaction complies with legal and tax regulations.
For example, recording a shareholder’s withdrawal of company funds for personal expenses under Account 131 does not eliminate the statutory conditions governing shareholder borrowing or the applicable tax obligations.
Is Interest Required on Shareholder Current Account Balances?
When a company lends money to a shareholder, the transaction may constitute a financing arrangement between related parties.
Article 13 of Corporate Tax Law No. 5520 regulates the arm’s length principle in transactions conducted between related parties.
Accordingly, the terms of financing provided by a company to its shareholder, including the applicable interest rate, may be subject to examination from a tax perspective.
Transactions conducted under conditions that do not comply with the arm’s length principle may give rise to the risk of disguised profit distribution through transfer pricing.
However, not every shareholder current account balance automatically requires interest to be calculated. The actual nature of the transaction, the existence of a lending relationship, its duration, and other relevant circumstances must be evaluated together.
Depending on the characteristics of the financing transaction, a separate assessment may also be necessary for Value Added Tax (VAT) purposes.
What Risks Arise from Uncontrolled Withdrawals of Company Funds?
The use of company resources by shareholders for personal expenses is not merely an accounting issue.
Such practices may result in:
- Increased documentation and justification requirements during tax audits,
- Assessments concerning arm’s length interest rates and transfer pricing,
- Allegations of disguised profit distribution,
- Deterioration of the company’s cash flow,
- Reduced reliability and accuracy of financial statements,
- Financial disputes among shareholders.
In particular, significant receivable balances from shareholders that remain outstanding for extended periods and lack a clear supporting basis should be carefully examined.
How Can Companies Manage These Risks?
To manage shareholder current accounts effectively, companies must first establish a clear separation between corporate financial resources and shareholders’ personal expenditures.
Cash outflows from the company should be regularly monitored, supporting documentation should be maintained, and shareholder current accounts should be periodically reviewed and reconciled.
For borrowing transactions, statutory requirements, compliance with the arm’s length principle, and potential tax consequences should be assessed in advance.
Furthermore, coordinating the company’s dividend distribution policy with shareholders’ financing needs can help prevent uncontrolled withdrawals of corporate funds.
Company Funds and Shareholders’ Personal Funds Are Not the Same
A company’s financial strength is determined not only by the profits it generates but also by how effectively it manages its resources.
When shareholders’ personal expenses become intertwined with corporate activities, significant tax and financial risks may emerge over time.
Effective financial management involves more than simply recording transactions in the accounting system. It requires a comprehensive evaluation of their legal basis, tax implications, and impact on the company’s financial position.
Relevant Legislation
Turkish Commercial Code No. 6102
- Article 358: Conditions governing borrowing by shareholders from the company.
- Article 644: Application of certain provisions governing joint-stock companies to limited liability companies.
- Articles 408, 608, and 616: Provisions concerning dividend distribution and the powers of the general assembly, depending on the type of company.
Corporate Tax Law No. 5520
– Article 13: Disguised profit distribution through transfer pricing and the arm’s length principle applicable to related-party transactions.
General Communiqué No. 1 on Disguised Profit Distribution Through Transfer Pricing
This communiqué provides explanations regarding the evaluation of transactions between related parties in accordance with the arm’s length principle.
This article has been prepared for general informational purposes only. The legal and tax implications of specific transactions should be assessed separately, taking into consideration the type of company, its financial position, and the particular characteristics of the transaction.
Contact Information
Telephone: +90 212 983 67 33
Mobile Phone: +90 507 127 31 21
Email: info@reditus.com.tr
Business Hours: 09:00 – 19:00 Monday – Saturday
Address: Osmaniye Fabrikalar Cd., Yaşam Sitesi, D Block, No: 10, 34550 Bakırköy, Istanbul, Türkiye